Data Center Energy Storage Systems Market by Energy Storage Technology (BESS, FESS, Supercapacitor), Data Center Type (Enterprise, Cloud & Hyperscale, Colocation), Application, Enterprise Vertical, and Region - Global Forecast to 2032

icon1
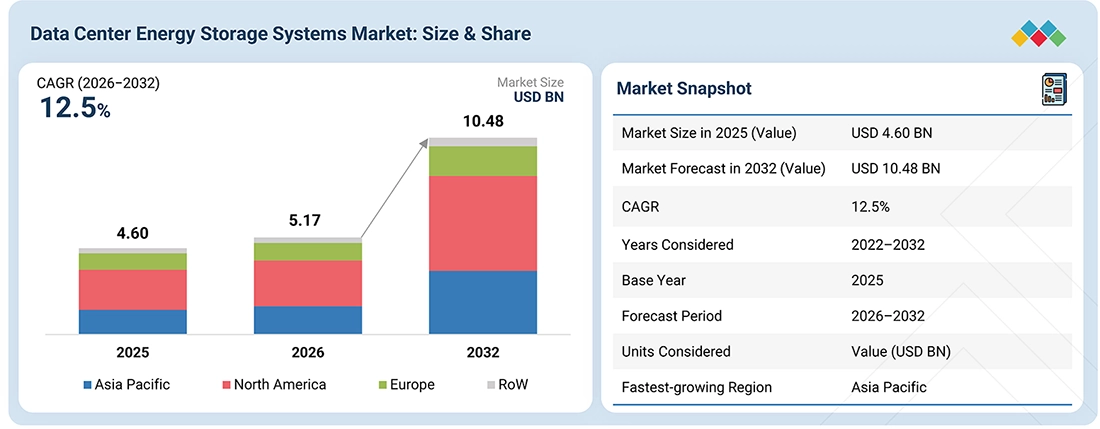
USD 10.48 BN
MARKET SIZE, 2032
icon2
CAGR 12.5%
(2026-2032)
icon3
275
REPORT PAGES
icon4
192
MARKET TABLES

DATA CENTER ENERGY STORAGE SYSTEMS MARKET

data center energy storage systems market

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis | Updated on : September 16, 2026

The global data center energy storage systems market is projected to grow from USD 5.17 billion in 2026 to USD 10.48 billion by 2032, at a CAGR of 12.5%. Energy storage systems are increasingly being integrated into data center power infrastructure to enhance energy reliability, operational flexibility, and power resilience. Technologies such as battery energy storage systems (BESS), flywheel energy storage systems (FESS), supercapacitors, and hydrogen-based storage can address diverse power requirements, with applications expanding beyond conventional backup power to include energy management, renewable energy integration, peak-load management, and grid support. This broader range of applications is creating additional demand for energy storage solutions across data center facilities. The rapid adoption of artificial intelligence (AI), cloud computing, and other power-intensive digital technologies is increasing data center electricity consumption and driving investments in supporting power infrastructure. At the same time, the growing integration of renewable energy into data center power supplies is increasing the need for energy storage to manage intermittency, balance supply and demand, and maintain reliable power availability. As data center operators face higher peak power requirements and increasingly complex energy management needs, energy storage systems are becoming an important component of resilient power infrastructure. Consequently, the expanding application of energy storage technologies, coupled with the continued growth of data center capacity and evolving electricity consumption patterns, is driving demand for energy storage systems in data center power networks.

KEY TAKEAWAYS

  • BY REGION
    The Asia Pacific region is expected to register the highest CAGR during the forecast period.
  • BY ENERGY STORAGE TECHNOLOGY
    By energy storage technology, the supercapacitor energy storage systems segment is expected to register the highest CAGR of 16.5% from 2026 to 2032.
  • BY DATA CENTER TYPE
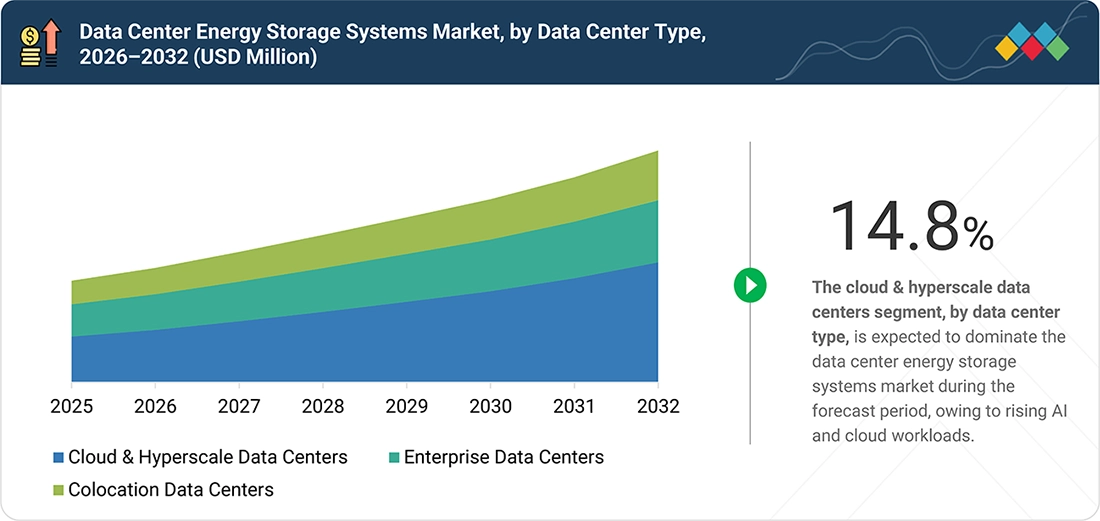
    By data center type, the cloud & hyperscale data centers segment is expected to register the highest CAGR of 14.8% between 2026 and 2032.
  • BY ENTERPRISE VERTICAL
    By enterprise vertical, the IT & telecommunications segment is expected to record the fastest growth during the forecast period.
  • BY APPLICATION
    By application, the renewable integration & grid services segment is expected to register the highest CAGR of 18.3% from 2026 to 2032.
  • BY POWER CAPACITY
    By power capacity, the 5–20 MW segment is expected to dominate the market.
  • BY COMPONENT AND MANAGEMENT SYSTEM
    By component and management system, energy storage device is expected to dominate the market.
  • Competitive Landscape - Key Players
    Tesla; Contemporary Amperex Technology Co., Limited.; LG Energy Solution; Samsung SDI Co., Ltd.; and Panasonic Holdings Corporation were identified as some of the leading players in the data center energy storage systems market, given their strong market share and product footprint.
  • Competitive Landscape - Startups
    ZincFive, Inc.; Active Power Inc.; and Skeleton Technologies, among others, have become leading startups or SMEs because they identify niche gaps early and deliver solutions that precisely match unmet customer needs. Their agility, faster decision-making, and ability to innovate continuously allow them to outperform larger, less flexible competitors.

Energy storage systems are becoming more important for data center operations as these centers need to reinforce their power infrastructure in response to changing power capacity demands, as well as different types of data centers and industry verticals. The demand for energy storage systems is driven by the growth in the number of hyperscale, colocation, and enterprise data centers, as companies from the BFSI, healthcare & life sciences, manufacturing, e-commerce & retail, and IT & telecommunications verticals increasingly rely on a stable digital infrastructure. The rapid development of AI and cloud solutions brings about an increasing need for extra data center facilities and, thus, reliable power sources. At the same time, constraints on grid availability push providers to look for onsite energy solutions for the construction or development of their data centers. The rise of popularity of renewable energy makes energy storage interesting in the light of bigger energy strategies of data centers.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

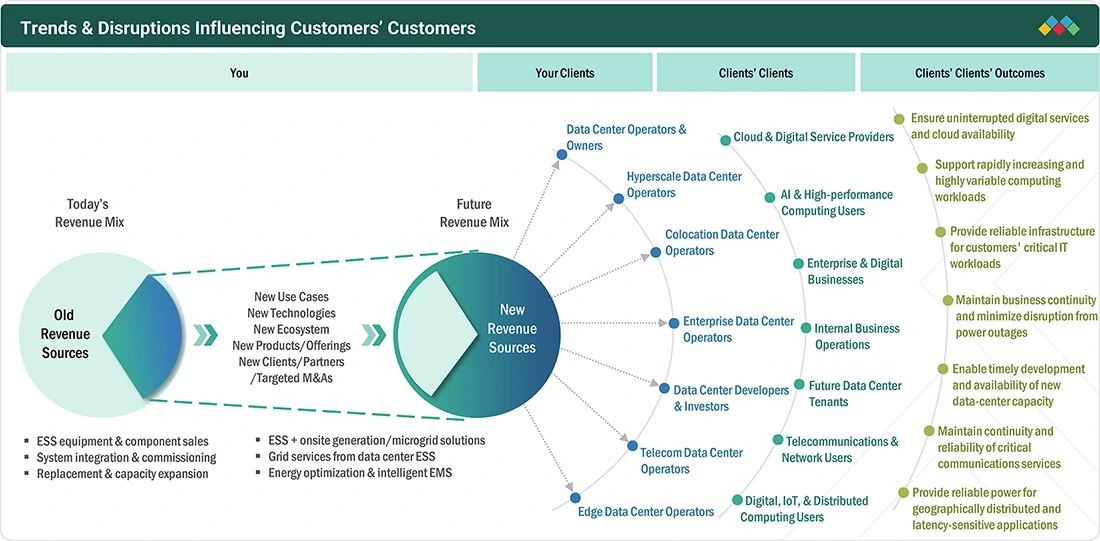
The impact on consumers' businesses arises from evolving customer trends or market disruptions. Megatrends such as sustainability and digital transformation, alongside disruptions such as AI, supply chain localization, and energy transition, are significantly reshaping customer priorities and business models. Traditionally, revenue mixes were dominated by legacy products and processes focused on volume and cost. Today, customers are shifting toward high-margin, innovation-driven, and sustainable solutions to remain competitive and future-proof. This transition is prompting businesses to adapt quickly, invest in cleaner technologies, and enhance agility, with suppliers expected to deliver compliant, efficient, and tech-enabled offerings that align with evolving market demands.

data-center-energy-storage-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Accelerating Investments in AI-driven and Hyperscale Data Center Infrastructure
  • Broadening ESS Adoption Across Backup, Energy Optimization, and Grid-Support Applications
RESTRAINTS
Impact
Level
  • High Upfront Capital Requirements for Data Center ESS Deployment
OPPORTUNITIES
Impact
Level
  • Growing Retrofit Demand for Power Density and Resilience
  • Emergence of Hybrid ESS Architectures for Diverse Data Center Needs
CHALLENGES
Impact
Level
  • Complex ESS Integration with Existing Data Center Infrastructure
  • Safety and Thermal Management Across ESS Technologies

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Accelerating Investments in AI-driven and Hyperscale Data Center Infrastructure

Accelerating investment in AI-driven and hyperscale data center infrastructure is driving demand for energy storage systems (ESS) as higher computing workloads increase power requirements and reliability needs. AI, cloud computing, and data-intensive workloads are prompting operators to develop larger, higher-density facilities that require dependable and flexible power infrastructure. ESS supports backup power, peak-load management, power fluctuation mitigation, and improved utilization of available electricity. The expansion of hyperscale facilities is further creating opportunities for larger-scale ESS deployments, while AI-driven growth is supporting both new data center construction and upgrades to existing facilities. In addition, increasing strain on grid infrastructure in key data center locations is encouraging operators to deploy onsite energy storage, further expanding the addressable demand for ESS.

Restraint: High Upfront Capital Requirements for Data Center ESS Deployment

High upfront capital requirements remain a key restraint for data center energy storage system (ESS) adoption, as ESS adds significant investment to already capital-intensive data center construction and expansion projects. Operators must balance ESS spending against investments in computing, power, cooling, networking, and other infrastructure, making the initial cost particularly challenging for smaller or capital-constrained facilities. High costs can also limit retrofit deployments, as operators must account for infrastructure modifications and installation complexity. Project economics further vary with electricity prices, operating requirements, and the value derived from resilience, energy flexibility, and renewable integration. Consequently, some operators may prioritize conventional power infrastructure, deploy ESS only for critical applications, or defer investments until the long-term economic benefits become more compelling.

Opportunity: Growing Retrofit Demand for Power Density and Resilience

Rising demand for retrofits in existing data centers is creating an opportunity for energy storage system (ESS) providers as operators modernize facilities to accommodate growing computational and power requirements. The expansion of AI, cloud computing, and other data-intensive workloads is placing greater pressure on existing infrastructure, increasing the need for energy storage to enhance power resilience, flexibility, and capacity without extensive reconstruction. This opportunity is particularly relevant where new data center development is constrained by limited grid access, land availability, or lengthy development timelines. As operators prioritize reliable digital services and upgrade aging power infrastructure, ESS providers can address both retrofit and expansion projects, expanding their customer base and creating additional growth opportunities.

Challenge: Safety and Thermal Management Across ESS Technologies

Safety and thermal management across ESS technologies pose key challenges for data center energy storage deployment, given the need for high reliability and uninterrupted power. Suppliers must address technology-specific safety and thermal requirements across BESS, FESS, supercapacitors, hydrogen, and UPS while maintaining consistent reliability standards. Heat management and safe operating conditions can increase installation, monitoring, and maintenance complexity, particularly in large, high-density data centers where safety incidents could disrupt critical operations. Stringent safety requirements may also influence technology selection, particularly for less-established solutions, while compliance with facility specifications can extend project timelines and increase deployment complexity.

DATA CENTER ENERGY STORAGE SYSTEMS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Energy storage systems are used in data centers to provide backup power, manage periods of high electricity demand, and support greater flexibility in how electricity is used. Improves power reliability | Supports operational continuity | Provides greater flexibility in energy management | Helps data centers respond to changing power requirements
company logo
Energy storage is incorporated into data center power infrastructure to support reliable operations, energy management, and the increasing use of renewable electricity. Helps improve resilience | Supports more efficient energy use | Facilitates integration of renewable energy | Provides greater visibility and control over energy resources
company logo
Energy storage solutions are used alongside data center power systems to provide backup support and help manage electricity demand and changing power requirements. Enhances power continuity | Provides additional flexibility in managing energy demand | Supports more efficient operation of data center infrastructure
company logo
Energy storage systems can be used to support data center power needs, including backup requirements, energy management, and integration with other onsite energy resources. Provides scalable energy storage, supports more effective energy management, and can improve the flexibility and reliability of power infrastructure
company logo
Energy storage solutions are used as part of integrated data center power infrastructure to support continuity of operations and manage the facility's energy requirements. Helps improve power availability | Supports efficient energy management | Enables greater flexibility as data center requirements increase | Contributes to more resilient infrastructure

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

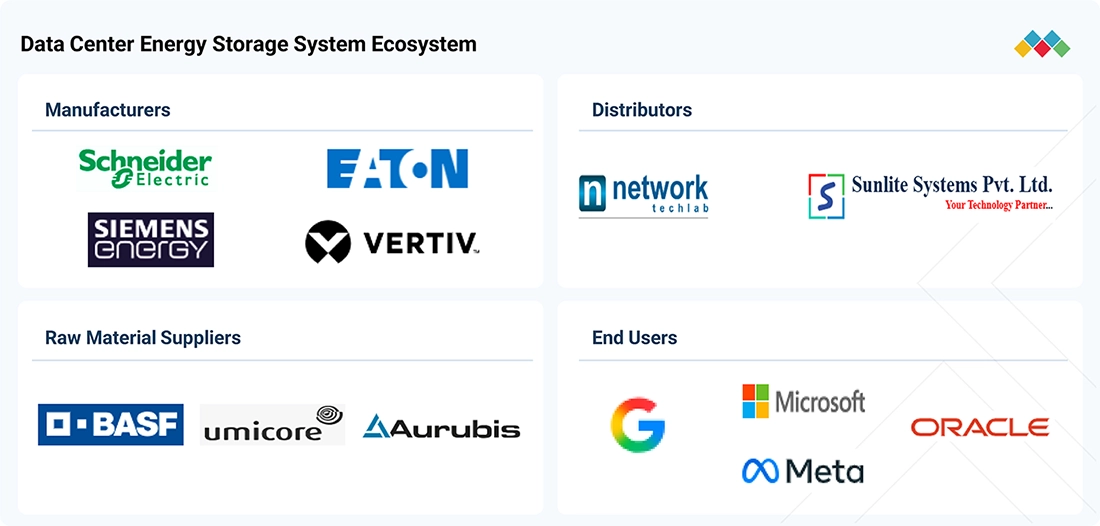
The data center energy storage systems ecosystem consists of raw material suppliers (e.g., Umicore, BASF SE, and Aurubis AG), system manufacturers (e.g., Schneider Electric, Eaton, Siemens Energy, and Vertiv Group Corp.), distributors (e.g., Network Techlab (India) Limited and Sunlite Systems Pvt. Ltd.), and end users (e.g. Google, Microsoft, Meta, and Oracle).

data-center-energy-storage-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

data-center-energy-storage-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Data Center Energy Storage Systems Market, By Data Center Type

The cloud and hyperscale data centers segment is likely to be the fastest-growing data center type, driven by rapid adoption of cloud computing, AI, and other data-intensive digital services. These facilities handle large workloads and require continuous modernization to meet rising demand for computing, storage, and interconnectivity. Increasing AI workload intensity is further raising electricity consumption and creating demand for reliable and flexible power infrastructure. ESS supports these requirements by providing backup power, power continuity, and greater flexibility in managing electricity consumption. Consequently, expanding cloud and hyperscale infrastructure and rising power requirements are driving ESS adoption.

Data Center Energy Storage Systems Market, By Application

The peak shaving & load management segment is likely to be the fastest-growing application, driven by expanding data center capacity and rising power requirements from AI, cloud computing, and other high-performance workloads. ESS enables operators to store electricity and discharge it during peak-demand periods, improving load management and reducing pressure on existing power infrastructure. This allows data centers to expand computing capacity without immediate upgrades to conventional power systems while improving energy efficiency and operational flexibility. As data centers increase in size and energy intensity, demand for peak shaving and load management solutions is expected to grow.

Data Center Energy Storage Systems Market, By Energy Storage Technology

The supercapacitor energy storage systems segment is anticipated to record the highest CAGR during the forecast period due to the rising power intensity of data centers, especially those that use high-performance computing and artificial intelligence (AI). The AI workloads result in rapid power fluctuations, pushing data centers to consider going for technologies that are competent enough to react to those fluctuations quickly. Supercapacitors are an ideal fit for this purpose due to their rapid power delivery capabilities and robustness, seeing as they can withstand frequent charge-discharge cycles. This complements conventional battery storage systems. Their increasing importance in terms of power quality management, peak shaving capabilities, and short-term power supply creates more opportunities for use. Thus, despite people's adoption of the AI network, the need for quick power storage also increases with time.

REGION

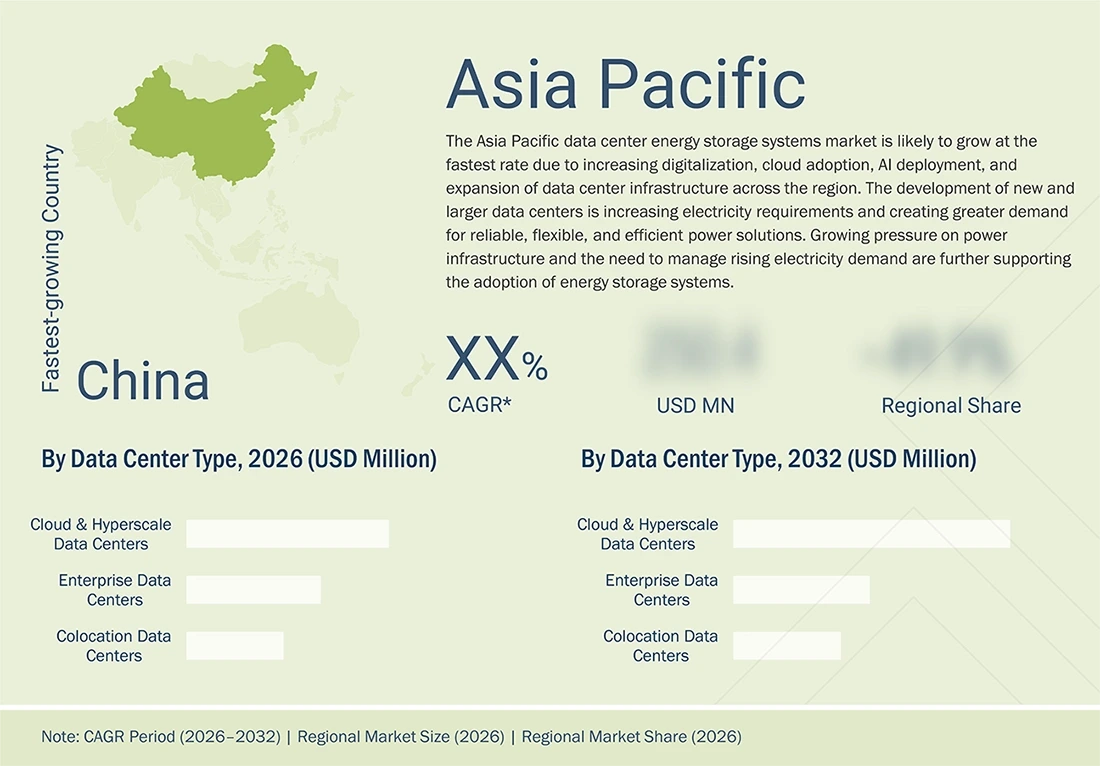
Asia Pacific to be fastest-growing region in global data center energy storage systems market during forecast period

Asia Pacific is likely to be the fastest-growing region, driven by rapid digitalization and rising demand for computing and data infrastructure. Growing adoption of cloud services, AI, online platforms, and digital applications is accelerating new data center construction and upgrades to existing facilities, increasing power requirements. As capacity expands, operators are prioritizing power availability and efficient electricity management, driving ESS adoption for backup power, resilience, demand management, and energy efficiency. Rapid digital infrastructure development is also encouraging ESS integration during the planning of new data centers.

data-center-energy-storage-market Region

DATA CENTER ENERGY STORAGE SYSTEMS MARKET: COMPANY EVALUATION MATRIX

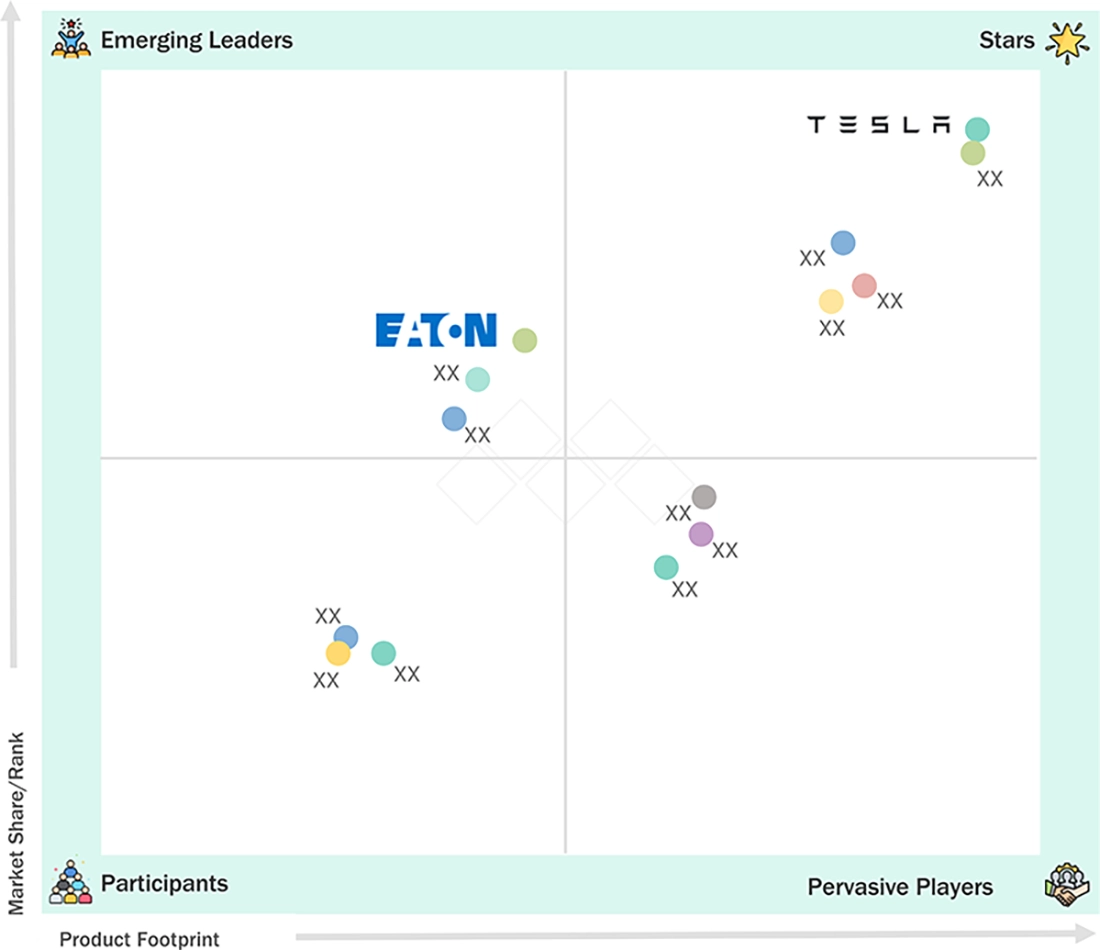
Tesla is a leading player in energy storage, supported by its large-scale battery storage capabilities and integrated energy management solutions for power-intensive data centers. Eaton is an emerging leader, leveraging its expertise in UPS, energy storage, power management, and data center services to address power reliability and energy management requirements. Both companies are well positioned to benefit from rising demand for energy-efficient and resilient data center power infrastructure and ESS solutions.

data-center-energy-storage-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 4.60 BN
Market Size in 2026 (Value) USD 5.17 BN
Market Forecast in 2032 (Value) USD 10.48 BN
CAGR (2026–2032) 12.5%
Years Considered 2022–2032
Base Year 2025
Forecast Period 2026–2032
Units Considered Value (USD Million)
Report Coverage Revenue forecast, competitive landscape, growth factors, and trends
Segments Covered By Energy Storage Technology: Battery Energy Storage Systems (BESS), Flywheel Energy Storage Systems (FESS), Supercapacitor Energy Storage Systems, Other Energy Storage Technologies (Hydrogen Energy Storage Systems, Superconducting Magnetic Energy Storage Systems, and Compressed Air Energy Storage Systems)
Regions Covered North America, Europe, Asia Pacific, and Rest of the World

WHAT IS IN IT FOR YOU: DATA CENTER ENERGY STORAGE SYSTEMS MARKET REPORT CONTENT GUIDE

data-center-energy-storage-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
A hyperscale data center operator needed to assess suitable energy storage technologies for expanding facilities. Evaluated the market across BESS, FESS, supercapacitor, hydrogen, and TES, with emphasis on their relevance to data center requirements Helps identify suitable technology pathways and prioritize areas for future investment
A data center infrastructure developer needed to identify applications with the strongest ESS adoption potential. Assessed power quality conditioning, extended backup power (UPS companion), peak shaving & load management, renewable integration & grid services, and black start Enables prioritization of applications based on their relevance to evolving data center power requirements
A cloud and digital services provider needed to understand ESS demand across different data center configurations. Assessed demand across enterprise, hyperscale, and colocation data centers and different power-capacity ranges Provides visibility into customer segments and facility types with stronger ESS deployment potential
A data center energy solutions provider needed to understand the factors influencing ESS market growth and adoption. Developed a tailored DROC analysis covering market-specific drivers, restraints, opportunities, and challenges Provides a structured view of market dynamics and helps identify areas requiring strategic focus.
A data center operator needed to identify ESS opportunities within its existing installed base. Assessed the growing retrofit opportunity as existing facilities adapt to higher power density, AI workloads, and resilience requirements Expands the addressable opportunity beyond new-build data centers and highlights potential demand from facility modernization.
An ESS manufacturer needed to understand routes to market and the broader supply ecosystem for data center applications. Mapped ESS producers, battery manufacturers, distributors, channel partners, and other relevant supply-chain participants Improves understanding of market structure, potential distribution channels, and opportunities for market expansion

RECENT DEVELOPMENTS

  • June 2026 : Schneider Electric launched the ASCO 300 SERIES Multi-Voltage Transfer Switch to simplify commercial backup power deployment across multiple voltages. This technology is applicable to data center backup power architectures that rely on battery-based UPS and generator systems.
  • June 2026 : Tesla and NatPower initiated the first phase of a USD 5-billion project to deploy 25 GWh of Tesla Megapack battery storage in Italy and Britain. These large-scale systems will enhance grid stability and meet the increasing power demands of data centers and other large-load applications.
  • March 2026 : Panasonic announced plans to significantly expand lithium-ion battery production capacity to meet rising demand from data center energy storage and backup systems.
  • March 2026 : Samsung SDI expanded its ESS business in North America by supplying prismatic batteries produced at its StarPlus Energy plant in Indiana, supporting growing demand for large-scale energy storage driven by renewable energy and AI infrastructure.
  • July 2024 : LG Energy Solution introduced its lithium-ion UPS battery solution, designed to provide reliable emergency power for critical infrastructure, including data centers, IT systems, and telecommunications. The system offers higher energy efficiency, longer lifespan, and improved reliability compared to conventional lead-acid UPS batteries.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


27
2
EXECUTIVE SUMMARY


31
3
PREMIUM INSIGHTS


36
4
MARKET OVERVIEW
AI-driven investments and hybrid architectures redefine energy-efficient, resilient data center infrastructures.


40
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
ACCELERATING INVESTMENTS IN AI-DRIVEN AND HYPERSCALE DATA CENTER INFRASTRUCTURE


4.2.1.2
BROADENING ESS ADOPTION ACROSS BACKUP, ENERGY OPTIMIZATION, AND GRID-SUPPORT APPLICATIONS


4.2.1.3
GROWING SUSTAINABILITY AND ENERGY-EFFICIENCY REQUIREMENTS FOR DATA CENTERS


4.2.2
RESTRAINTS


4.2.2.1
HIGH UPFRONT CAPITAL REQUIREMENTS FOR DATA CENTER ESS DEPLOYMENT


4.2.3
OPPORTUNITIES


4.2.3.1
EMERGENCE OF HYBRID AND MULTI-TECHNOLOGY ESS ARCHITECTURES FOR DIVERSE DATA CENTER REQUIREMENTS


4.2.3.2
AI-ENABLED ENERGY MANAGEMENT AND PREDICTIVE MONITORING TO IMPROVE ESS PERFORMANCE AND LIFECYCLE ECONOMICS


4.2.3.3
GROWING RETROFIT DEMAND AS EXISTING DATA CENTERS ADAPT TO HIGHER POWER DENSITY AND RESILIENCE REQUIREMENTS


4.2.4
CHALLENGES


4.2.4.1
COMPLEX INTEGRATION OF ESS WITH EXISTING DATA CENTER POWER INFRASTRUCTURE


4.2.4.2
ENSURING SAFETY AND THERMAL MANAGEMENT ACROSS DIVERSE ESS TECHNOLOGIES


4.3
UNMET NEEDS AND WHITE SPACES


4.3.1
UNMET NEEDS IN DATA CENTER ENERGY STORAGE SYSTEM MARKET


4.3.2
WHITE SPACE OPPORTUNITIES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.4.1
INTERCONNECTED MARKETS


4.4.2
CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


4.5.1
KEY MOVES AND STRATEGIC FOCUS


5
INDUSTRY TRENDS
Navigate shifting industry dynamics with strategic insights on power, competition, and global economic trends.


50
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
BARGAINING POWER OF SUPPLIERS


5.1.2
BARGAINING POWER OF BUYERS


5.1.3
THREAT OF NEW ENTRANTS


5.1.4
THREAT OF SUBSTITUTES


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
GLOBAL MACROECONOMIC OUTLOOK


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS AND FORECAST


5.2.3
TRENDS IN GLOBAL MEDIA & ENTERTAINMENT INDUSTRY


5.2.4
TRENDS IN GLOBAL IT & TELECOMMUNICATIONS INDUSTRY


5.3
SUPPLY CHAIN ANALYSIS


5.3.1
RAW MATERIAL SUPPLY


5.3.2
COMPONENT & MANAGEMENT SYSTEM PRODUCTION


5.3.3
ENERGY STORAGE SYSTEM PRODUCTION & ASSEMBLY


5.4
DISTRIBUTION & LOGISTICS


5.4.1
SYSTEM INTEGRATION & INSTALLATION


5.4.2
END USERS/DATA CENTER OPERATORS


5.4.3
ECOSYSTEM ANALYSIS


5.5
PRICING ANALYSIS


5.5.1
AVERAGE SELLING PRICE TREND OF UPS-GRADE BATTERY PACKS, BY REGION, 2022–2025


5.5.2
PRICING RANGE OF LITHIUM-ION BATTERY PACKS, BY KEY PLAYER, 2025


5.6
TRADE ANALYSIS


5.6.1
IMPORT SCENARIO (HS CODE 850760)


5.6.2
EXPORT SCENARIO (HS CODE 850760)


5.7
KEY CONFERENCES AND EVENTS, 2026–2027


5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.9
INVESTMENT AND FUNDING SCENARIO


5.10
CASE STUDY ANALYSIS


5.10.1
VERTIV’S LITHIUM-ION BATTERY AND UPS SOLUTIONS ENABLE SPACE-EFFICIENT POWER PROTECTION AT DATAVITA’S DV2 DATA CENTER, SCOTLAND


5.10.2
VERTIV ENABLES SCALABLE AND ENERGY-EFFICIENT POWER INFRASTRUCTURE AT FORSYTHE DATA CENTERS


5.10.3
EATON ENABLES RENEWABLE ENERGY STORAGE AND INTELLIGENT POWER MANAGEMENT AT WEBAXYS DATA CENTER, FRANCE


5.11
IMPACT OF 2026 US TARIFF - DATA CENTER ENERGY STORAGE SYSTEM MARKET


5.12
KEY TARIFF RATES IMPACTING MARKET


5.13
PRICE IMPACT ANALYSIS


5.13.1
KEY IMPACT ON VARIOUS REGIONS


5.13.1.1
US


5.13.1.2
EUROPE


5.13.1.3
ASIA PACIFIC


5.14
IMPACT ON END-USE INDUSTRIES OF DATA CENTER ENERGY STORAGE SYSTEM MARKET


5.14.1
BFSI


5.14.2
HEALTHCARE & LIFE SCIENCES


5.14.3
MANUFACTURING


5.14.4
E-COMMERCE & RETAIL


5.14.5
MEDIA & ENTERTAINMENT


5.14.6
IT & TELECOMMUNICATIONS


5.14.7
GOVERNMENT & PUBLIC SECTOR


5.14.8
OTHER ENTERPRISE VERTICALS


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI and energy innovations revolutionize data centers with resilient, efficient, and intelligent power solutions.


70
 
6.1
KEY EMERGING TECHNOLOGIES


6.1.1
GRID-FORMING BATTERY ENERGY STORAGE SYSTEMS FOR DATA CENTERS


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
ADVANCED UPS SYSTEMS SUPPORTING DATA CENTER ENERGY STORAGE


6.3
TECHNOLOGY/PRODUCT ROADMAP


6.3.1
SHORT-TERM (2025–2027) | TECHNOLOGY OPTIMIZATION & DEPLOYMENT EXPANSION


6.3.2
MID-TERM (2027–2030) | SYSTEM INTEGRATION & PERFORMANCE ENHANCEMENT


6.3.3
LONG-TERM (2030–2035+) | ADVANCED STORAGE & INTELLIGENT ENERGY MANAGEMENT


6.4
PATENT ANALYSIS


6.4.1
METHODOLOGY


6.5
FUTURE APPLICATIONS


6.5.1
POWER QUALITY CONDITIONING: FAST POWER FLUCTUATION MANAGEMENT FOR AI WORKLOADS


6.5.2
EXTENDED BACKUP POWER: LONGER-DURATION BACKUP AND REDUCED GENERATOR DEPENDENCE


6.5.3
PEAK SHAVING AND LOAD MANAGEMENT: FLEXIBLE POWER DEMAND AND PEAK LOAD MANAGEMENT


6.5.4
RENEWABLE INTEGRATION AND GRID SERVICES: RENEWABLE ENERGY MATCHING AND GRID FLEXIBILITY


6.5.5
BLACK START: RESILIENT RESTART AND INDEPENDENT DATA CENTER OPERATION


6.6
IMPACT OF GENERATIVE AI ON DATA CENTER ENERGY STORAGE SYSTEM MARKET


6.6.1
INTRODUCTION


6.6.2
RISING POWER DEMAND AND STORAGE REQUIREMENTS


6.6.3
INCREASING NEED FOR FLEXIBLE POWER MANAGEMENT


6.6.4
DEVELOPMENT OF AI-SUITABLE ESS SOLUTIONS


6.6.5
GREATER INTEGRATION WITH RENEWABLE ENERGY AND PEAK MANAGEMENT


6.7
OVERALL MARKET IMPACT


7
REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
Navigate complex regulations to enhance sustainability and reduce carbon impact in data center energy storage.


82
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.1.3
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


7.2
SUSTAINABILITY INITIATIVES


7.2.1
CARBON IMPACT AND ECO-APPLICATIONS OF DATA CENTER ENERGY STORAGE SYSTEMS


7.2.1.1
CARBON IMPACT REDUCTION


7.2.1.2
ECO-APPLICATIONS


7.3
IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Unlock market profitability by addressing unmet needs and leveraging digitalization across diverse sectors.


88
 
8.1
INTRODUCTION


8.2
DECISION-MAKING PROCESS


8.2.1
KEY STAKEHOLDERS AND BUYING CRITERIA


8.2.2
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.3
BUYING CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS IN VARIOUS APPLICATIONS


8.5
MARKET PROFITABILITY


8.5.1
REVENUE POTENTIAL


8.5.2
COST DYNAMICS


8.5.3
MARGIN OPPORTUNITIES IN KEY APPLICATIONS


DATA CENTER ENERGY STORAGE SYSTEM MARKET,


9.1
INTRODUCTION


9.2
BFSI


9.2.1
GROWING DIGITALIZATION AND INCREASING RESILIENCE REQUIREMENTS


9.3
HEALTHCARE & LIFE SCIENCES


9.3.1
GROWING DIGITAL HEALTHCARE INFRASTRUCTURE AND INCREASING REQUIREMENTS FOR RELIABLE OPERATIONS


9.4
MANUFACTURING


9.4.1
GROWING INDUSTRIAL DIGITALIZATION AND INCREASING RELIANCE ON DATA-DRIVEN OPERATIONS


9.5
E-COMMERCE & RETAIL


9.5.1
GROWING DIGITAL COMMERCE AND INCREASING DEPENDENCE ON ALWAYS-ON DATA INFRASTRUCTURE


9.6
MEDIA & ENTERTAINMENT


9.6.1
GROWING DIGITAL MEDIA CONSUMPTION AND INCREASING DATA INFRASTRUCTURE REQUIREMENTS


9.7
IT & TELECOMMUNICATIONS


9.7.1
EXPANDING DIGITAL INFRASTRUCTURE AND RISING DATA CENTER POWER REQUIREMENTS


9.8
GOVERNMENT & PUBLIC SECTOR


9.8.1
GROWING GOVERNMENT DIGITALIZATION AND INCREASING RESILIENCE REQUIREMENTS


9.9
OTHER ENTERPRISE VERTICALS/END USERS


10
ENERGY STORAGE SYSTEMS MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2032 in USD Million | 12 Data Tables


103
 
10.1
INTRODUCTION


10.2
POWER QUALITY CONDITIONING


10.2.1
RISING DATA CENTER POWER INTENSITY AND GROWING REQUIREMENTS FOR RELIABLE POWER


10.3
EXTENDED BACKUP POWER (UPS COMPANION)


10.3.1
GROWING DATA CENTER POWER REQUIREMENTS AND INCREASING RESILIENCE NEEDS


10.4
PEAK SHAVING AND LOAD MANAGEMENT


10.4.1
RISING DATA CENTER ELECTRICITY DEMAND AND GROWING FOCUS ON ENERGY COST AND DEMAND MANAGEMENT


10.5
RENEWABLE INTEGRATION AND GRID SERVICES


10.5.1
GROWING RENEWABLE ENERGY ADOPTION AND INCREASING FOCUS ON FLEXIBLE ELECTRICITY MANAGEMENT


10.6
BLACK START


10.6.1
GROWING DATA CENTER RESILIENCE REQUIREMENTS AND INCREASING FOCUS ON RAPID POWER RESTORATION


DATA CENTER ENERGY STORAGE SYSTEM MARKET,


11.1
INTRODUCTION


11.2
BATTERY ENERGY STORAGE SYSTEMS (BESS)


11.2.1
GROWING DATA CENTER POWER REQUIREMENTS AND NEED FOR RELIABLE, RESILIENT, AND FLEXIBLE ENERGY MANAGEMENT


11.3
FLYWHEEL ENERGY STORAGE SYSTEMS (FESS)


11.3.1
GROWING DEMAND FOR RAPID AND RELIABLE POWER SUPPORT IN DATA CENTERS


11.4
SUPERCAPACITOR ENERGY STORAGE SYSTEMS


11.4.1
GROWING DEMAND FOR RAPID POWER SUPPORT AND IMPROVED POWER QUALITY IN DATA CENTERS


11.5
OTHER ENERGY STORAGE TECHNOLOGIES


12
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE
Market Size & Growth Rate Forecast Analysis to 2032 in USD Million | 8 Data Tables


115
 
12.1
INTRODUCTION


12.2
ENTERPRISE DATA CENTERS


12.2.1
GROWING ENTERPRISE RELIANCE ON DIGITAL INFRASTRUCTURE AND RISING DATA CENTER POWER REQUIREMENTS


12.3
CLOUD & HYPERSCALE DATA CENTERS


12.3.1
GROWING CLOUD AND AI-DRIVEN COMPUTING REQUIREMENTS EXPANDING LARGE-SCALE DATA CENTER INFRASTRUCTURE


12.4
COLOCATION DATA CENTERS


12.4.1
GROWING DEMAND FOR COLOCATION CAPACITY AND INCREASING POWER REQUIREMENTS


13
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY POWER CAPACITY
Market Size & Growth Rate Forecast Analysis


121
 
13.1
INTRODUCTION


13.2
BELOW 1 MW


13.2.1
GROWING ADOPTION OF ESS ACROSS SMALLER DATA CENTERS AND TARGETED APPLICATIONS


13.3
1–5 MW


13.3.1
DATA CENTER EXPANSION AND BROADER ESS ADOPTION ACROSS MULTIPLE APPLICATIONS


13.4
5–20 MW


13.4.1
RISING DATA CENTER POWER REQUIREMENTS AND BROADER USE OF ESS FOR ENERGY MANAGEMENT


13.5
ABOVE 20 MW


13.5.1
EXPANDING HYPERSCALE AND AI-DRIVEN DATA CENTERS WITH RISING POWER REQUIREMENTS


DATA CENTER ENERGY STORAGE SYSTEM MARKET,


14.1
INTRODUCTION


14.2
ENERGY STORAGE DEVICES


14.2.1
RISING DATA CENTER ENERGY REQUIREMENTS AND DEMAND FOR RELIABLE, FLEXIBLE STORAGE


14.3
POWER CONVERSION SYSTEMS


14.3.1
GROWING ESS DEPLOYMENT AND NEED TO INTEGRATE STORAGE RELIABLY WITH DATA CENTER POWER INFRASTRUCTURE


14.4
COOLING AND VENTILATION SYSTEMS


14.4.1
INCREASING ESS SCALE AND OPERATING INTENSITY


14.5
INTEGRATED FIRE DETECTION AND SUPPRESSION SYSTEMS


14.5.1
GROWING ESS DEPLOYMENT AND RISING DATA CENTER SAFETY REQUIREMENTS


14.5.2
HEAT, SMOKE, AND GAS SENSORS


14.5.3
ANTI-DEFLAGRATION SYSTEMS


14.6
ELECTRICAL PROTECTION SYSTEMS


14.6.1
GROWING DATA CENTER POWER DEMAND AND NEED FOR RELIABLE ESS INTEGRATION


14.6.2
CIRCUIT BREAKERS


14.6.3
FUSES


14.6.4
SURGE PROTECTORS


14.7
CONTROL AND MONITORING SYSTEMS


14.7.1
GROWING DATA CENTER POWER COMPLEXITY AND NEED FOR GREATER ESS VISIBILITY AND CONTROL


14.8
ENERGY MANAGEMENT SYSTEMS


14.8.1
RISING DATA CENTER ENERGY DEMAND AND GROWING FOCUS ON ENERGY OPTIMIZATION


14.9
OTHER COMPONENTS AND MANAGEMENT SYSTEMS


15
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 14 Countries | 62 Data Tables.


128
 
15.1
INTRODUCTION


15.2
NORTH AMERICA


15.2.1
US


15.2.1.1
RISING ELECTRICITY DEMAND FROM AI AND EXPANDING DATA CENTER INFRASTRUCTURE TO DRIVE ESS ADOPTION AND US MARKET GROWTH


15.2.2
CANADA


15.2.2.1
RAPID DATA CENTER EXPANSION AND RISING ELECTRICITY REQUIREMENTS TO ACCELERATE ESS DEPLOYMENT ACROSS CANADA


15.2.3
MEXICO


15.2.3.1
RAPID DATA CENTER INVESTMENT DRIVEN BY DIGITALIZATION, AI, AND NEARSHORING TO SPUR ESS DEMAND IN MEXICO


15.3
ASIA PACIFIC


15.3.1
CHINA


15.3.1.1
RAPID DATA INFRASTRUCTURE EXPANSION AND GROWING COMPUTING CAPACITY TO FUEL ESS ADOPTION ACROSS CHINA


15.3.2
JAPAN


15.3.2.1
GROWING AI ADOPTION AND DATA CENTER INFRASTRUCTURE DEVELOPMENT TO BOOST ENERGY STORAGE DEPLOYMENT IN JAPAN


15.3.3
INDIA


15.3.3.1
RAPID DATA CENTER EXPANSION AND RISING ELECTRICITY DEMAND FROM AI TO PROPEL ESS ADOPTION IN INDIA


15.3.4
SOUTH KOREA


15.3.4.1
RAPID AI INFRASTRUCTURE EXPANSION AND RISING DATA CENTER ELECTRICITY DEMAND TO STRENGTHEN ESS DEMAND IN SOUTH KOREA


15.3.5
AUSTRALIA


15.3.5.1
GROWING DATA CENTER CAPACITY AND RISING ELECTRICITY REQUIREMENTS TO LIFT ESS UPTAKE ACROSS AUSTRALIA


15.3.6
REST OF ASIA PACIFIC


15.4
EUROPE


15.4.1
GERMANY


15.4.1.1
PLANNED DATA CENTER EXPANSION AND RISING ELECTRICITY REQUIREMENTS DRIVEN BY AI TO UNDERPIN ESS MARKET GROWTH IN GERMANY


15.4.2
UK


15.4.2.1
GROWING AI AND DATA CENTER INFRASTRUCTURE AND RISING ELECTRICITY REQUIREMENTS TO STIMULATE ESS DEMAND IN UK


15.4.3
FRANCE


15.4.3.1
AI, CLOUD, AND DIGITAL SERVICES EXPANDING DATA CENTER INFRASTRUCTURE TO ADVANCE ESS ADOPTION IN FRANCE


15.4.4
NETHERLANDS


15.4.4.1
RISING DATA CENTER ELECTRICITY CONSUMPTION AND INCREASING POWER REQUIREMENTS TO EXPAND ESS DEPLOYMENT IN NETHERLANDS


15.4.5
SPAIN


15.4.5.1
RISING DIGITALIZATION AND COMPUTING DEMAND TO REINFORCE ESS DEMAND IN SPAIN


15.4.6
ITALY


15.4.6.1
LARGER, MORE POWER-INTENSIVE DATA CENTERS TO AMPLIFY ESS DEMAND IN ITALY


15.4.7
REST OF EUROPE


15.5
REST OF THE WORLD


15.5.1
MIDDLE EAST & AFRICA


15.5.2
SOUTH AMERICA


16
COMPETITIVE LANDSCAPE
Uncover top players' strategies and market dominance in energy storage systems.


160
 
16.1
INTRODUCTION


16.2
KEY PLAYER STRATEGIES/RIGHT TO WIN


16.3
REVENUE ANALYSIS


16.3.1
TOP 5 PLAYERS’ REVENUE ANALYSIS


16.4
MARKET SHARE ANALYSIS


16.4.1
RANKING OF KEY MARKET PLAYERS, 2025


16.4.2
MARKET SHARE OF KEY PLAYERS


16.5
PRODUCT COMPARISON


16.5.1
ENERGY STORAGE SYSTEM


16.5.2
ESS


16.5.3
ESS BATTERIES


16.5.4
MEGAPACK


16.5.5
ENERGY STORAGE SYSTEM


16.6
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


16.6.1
STARS


16.6.2
EMERGING LEADERS


16.6.3
PERVASIVE PLAYERS


16.6.4
PARTICIPANTS


16.6.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


16.6.5.1
COMPANY FOOTPRINT


16.6.5.2
REGION FOOTPRINT


16.6.5.3
ENERGY STORAGE TECHNOLOGY FOOTPRINT


16.6.5.4
DATA CENTER TYPE FOOTPRINT


16.6.5.5
POWER CAPACITY FOOTPRINT


16.7
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


16.7.1
PROGRESSIVE COMPANIES


16.7.2
RESPONSIVE COMPANIES


16.7.3
DYNAMIC COMPANIES


16.7.4
STARTING BLOCKS


16.7.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


16.7.5.1
DETAILED LIST OF KEY STARTUPS/SMES


16.7.6
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


16.8
COMPETITIVE SCENARIO


16.8.1
PRODUCT LAUNCHES


16.8.2
DEALS


16.8.3
EXPANSIONS


16.9
VALUATION AND FINANCIAL METRICS


17
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


181
 
17.1
KEY PLAYERS


17.1.1
TESLA


17.1.1.1
BUSINESS OVERVIEW


17.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


17.1.1.3
RECENT DEVELOPMENTS


17.1.1.3.1
DEALS


17.1.1.4
MNM VIEW


17.1.1.4.1
KEY STRENGTHS


17.1.1.4.2
STRATEGIC CHOICES


17.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS


17.1.2
PANASONIC HOLDINGS CORPORATION


17.1.3
SAMSUNG SDI CO., LTD.


17.1.4
LG ENERGY SOLUTION


17.1.5
CONTEMPORARY AMPEREX TECHNOLOGY CO., LIMITED


17.1.6
BYD COMPANY LTD.


17.1.7
SCHNEIDER ELECTRIC


17.1.8
VERTIV GROUP CORP.


17.1.9
EATON


17.1.10
ABB


17.1.11
SIEMENS ENERGY


17.1.12
DELTA ELECTRONICS, INC.


17.1.13
HITACHI ENERGY LTD


17.1.14
FLUENCE


17.1.15
SAFT


17.1.16
WÄRTSILÄ


17.1.17
ENERSYS


17.1.18
HUAWEI DIGITAL POWER TECHNOLOGIES CO., LTD.


17.1.19
GS YUASA


17.1.20
EXIDE TECHNOLOGIES


17.1.21
TOSHIBA INTERNATIONAL CORPORATION


17.2
OTHER PLAYERS


17.2.1
EAST PENN MANUFACTURING COMPANY


17.2.2
ZINCFIVE, INC.


17.2.3
ACTIVE POWER INC.


17.2.4
SKELETON TECHNOLOGIES


17.2.5
VYCON


18
RESEARCH METHODOLOGY


265
 
18.1
RESEARCH DATA


18.1.1
SECONDARY DATA


18.1.2
PRIMARY DATA


18.1.2.1
LIST OF PRIMARY INTERVIEW PARTICIPANTS (DEMAND AND SUPPLY SIDES)


18.2
MARKET SIZE ESTIMATION


18.2.1
BOTTOM-UP APPROACH


18.2.2
TOP-DOWN APPROACH


18.2.2.1
CALCULATIONS FOR SUPPLY-SIDE ANALYSIS


18.3
GROWTH FORECAST


18.4
DATA TRIANGULATION


19
APPENDIX


275
 
19.1
DISCUSSION GUIDE


19.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


19.3
CUSTOMIZATION OPTIONS


19.4
RELATED REPORTS


19.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
DATA CENTER ENERGY STORAGE SYSTEM MARKET: PORTER’S FIVE FORCES ANALYSIS


TABLE 2
REAL GDP GROWTH (ANNUAL PERCENTAGE CHANGE), BY COUNTRY, 2022–2025 (%)


TABLE 3
UNEMPLOYMENT RATE, BY COUNTRY, 2022–2025 (%)


TABLE 4
INFLATION RATE, AVERAGE CONSUMER PRICES, BY COUNTRY, 2022–2025 (%)


TABLE 5
FOREIGN DIRECT INVESTMENT, BY REGION, 2022–2024 (USD BILLION)


TABLE 6
ROLES OF COMPANIES IN DATA CENTER ENERGY STORAGE SYSTEMS ECOSYSTEM


TABLE 7
AVERAGE SELLING PRICE TREND OF UPS-GRADE BATTERY PACKS, BY REGION, 2022–2025 (USD/KWH)


TABLE 8
PRICING RANGE OF LITHIUM-ION BATTERY PACKS OFFERED BY KEY PLAYERS, 2025


TABLE 9
IMPORT DATA FOR HS CODE 850760, BY KEY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 10
EXPORT DATA FOR HS CODE 850760, BY KEY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 11
DATA CENTER ENERGY STORAGE SYSTEM MARKET: KEY CONFERENCES AND EVENTS, 2026–2027


TABLE 12
DATA CENTER ENERGY STORAGE SYSTEM MARKET: LIST OF MAJOR PATENTS, 2015–2025


TABLE 13
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 14
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 15
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 16
GLOBAL STANDARDS IN DATA CENTER ENERGY STORAGE SYSTEM MARKET


TABLE 17
CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN DATA CENTER ENERGY STORAGE SYSTEM MARKET


TABLE 18
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY APPLICATIONS (%)


TABLE 19
KEY BUYING CRITERIA, BY APPLICATIONS


TABLE 20
DATA CENTER ENERGY STORAGE SYSTEM MARKET: UNMET NEEDS IN KEY APPLICATIONS


TABLE 21
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENTERPRISE VERTICAL/END USER, 2022–2025 (USD MILLION)


TABLE 22
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENTERPRISE VERTICAL/END USER, 2026–2032 (USD MILLION)


TABLE 23
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 24
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY APPLICATION, 2026–2032 (USD MILLION)


TABLE 25
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 26
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 27
BATTERY ENERGY STORAGE SYSTEMS (BESS): DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 28
BATTERY ENERGY STORAGE SYSTEMS (BESS): DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2026–2032 (USD MILLION)


TABLE 29
FLYWHEEL ENERGY STORAGE SYSTEMS (FESS): DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 30
FLYWHEEL ENERGY STORAGE SYSTEMS (FESS): DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2026–2032 (USD MILLION)


TABLE 31
SUPERCAPACITOR ENERGY STORAGE SYSTEMS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 32
SUPERCAPACITOR ENERGY STORAGE SYSTEMS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2026–2032 (USD MILLION)


TABLE 33
OTHER ENERGY STORAGE TECHNOLOGIES: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 34
OTHER ENERGY STORAGE TECHNOLOGIES: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2026–2032 (USD MILLION)


TABLE 35
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2022–2025 (USD MILLION)


TABLE 36
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2026–2032 (USD MILLION)


TABLE 37
ENTERPRISE DATA CENTERS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 38
ENTERPRISE DATA CENTERS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2026–2032 (USD MILLION)


TABLE 39
CLOUD & HYPERSCALE DATA CENTERS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 40
CLOUD & HYPERSCALE DATA CENTERS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2026–2032 (USD MILLION)


TABLE 41
COLOCATION DATA CENTERS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 42
COLOCATION DATA CENTERS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2026–2032 (USD MILLION)


TABLE 43
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 44
DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY REGION, 2026–2032 (USD MILLION)


TABLE 45
NORTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 46
NORTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY COUNTRY, 2026–2032 (USD MILLION)


TABLE 47
NORTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 48
NORTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 49
NORTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2022–2025 (USD MILLION)


TABLE 50
NORTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2026–2032 (USD MILLION)


TABLE 51
US: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 52
US: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 53
CANADA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 54
CANADA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 55
MEXICO: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 56
MEXICO: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 57
ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 58
ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY COUNTRY, 2026–2032 (USD MILLION)


TABLE 59
ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 60
ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 61
ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2022–2025 (USD MILLION)


TABLE 62
ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2026–2032 (USD MILLION)


TABLE 63
CHINA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 64
CHINA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 65
JAPAN: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 66
JAPAN: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 67
INDIA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 68
INDIA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 69
SOUTH KOREA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 70
SOUTH KOREA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 71
AUSTRALIA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 72
AUSTRALIA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 73
REST OF ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 74
REST OF ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 75
EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 76
EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY COUNTRY, 2026–2032 (USD MILLION)


TABLE 77
EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 78
EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 79
EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2022–2025 (USD MILLION)


TABLE 80
EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2026–2032 (USD MILLION)


TABLE 81
GERMANY: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 82
GERMANY: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 83
UK: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 84
UK: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 85
FRANCE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 86
FRANCE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 87
NETHERLANDS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 88
NETHERLANDS: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 89
SPAIN: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 90
SPAIN: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 91
ITALY: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 92
ITALY: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 93
REST OF EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 94
REST OF EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 95
REST OF THE WORLD: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 96
REST OF THE WORLD: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY COUNTRY, 2026–2032 (USD MILLION)


TABLE 97
REST OF THE WORLD: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 98
REST OF THE WORLD: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 99
REST OF THE WORLD: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2022–2025 (USD MILLION)


TABLE 100
REST OF THE WORLD: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY DATA CENTER TYPE, 2026–2032 (USD MILLION)


TABLE 101
MIDDLE EAST & AFRICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 102
MIDDLE EAST & AFRICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 103
SOUTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 104
SOUTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET, BY ENERGY STORAGE TECHNOLOGY, 2026–2032 (USD MILLION)


TABLE 105
DATA CENTER ENERGY STORAGE SYSTEM MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, (2021–2026)


TABLE 106
DATA CENTER ENERGY STORAGE SYSTEM MARKET: DEGREE OF COMPETITION, 2025


TABLE 107
DATA CENTER ENERGY STORAGE SYSTEM MARKET: REGION FOOTPRINT


TABLE 108
DATA CENTER ENERGY STORAGE SYSTEM MARKET: ENERGY STORAGE TECHNOLOGY FOOTPRINT


TABLE 109
DATA CENTER ENERGY STORAGE SYSTEM MARKET: DATA CENTER TYPE FOOTPRINT


TABLE 110
DATA CENTER ENERGY STORAGE SYSTEM MARKET: POWER CAPACITY FOOTPRINT


TABLE 111
DATA CENTER ENERGY STORAGE SYSTEM MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 112
DATA CENTER ENERGY STORAGE SYSTEM MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (1/2)


TABLE 113
DATA CENTER ENERGY STORAGE SYSTEM MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (2/2)


TABLE 114
DATA CENTER ENERGY STORAGE SYSTEM MARKET: PRODUCT LAUNCHES, 2021–2026


TABLE 115
DATA CENTER ENERGY STORAGE SYSTEM MARKET: DEALS, 2021–2026


TABLE 116
DATA CENTER ENERGY STORAGE SYSTEM MARKET: EXPANSIONS, 2021– 2026


TABLE 117
TESLA: COMPANY OVERVIEW


TABLE 118
TESLA: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 119
TESLA: DEALS, JANUARY 2021–AUGUST 2026


TABLE 120
PANASONIC HOLDINGS CORPORATION: COMPANY OVERVIEW


TABLE 121
PANASONIC HOLDINGS CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 122
PANASONIC HOLDINGS CORPORATION: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 123
SAMSUNG SDI CO., LTD.: COMPANY OVERVIEW


TABLE 124
SAMSUNG SDI CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 125
SAMSUNG SDI CO., LTD.: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 126
LG ENERGY SOLUTION: COMPANY OVERVIEW


TABLE 127
LG ENERGY SOLUTION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 128
LG ENERGY SOLUTION: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 129
CONTEMPORARY AMPEREX TECHNOLOGY CO., LIMITED: COMPANY OVERVIEW


TABLE 130
CONTEMPORARY AMPEREX TECHNOLOGY CO., LIMITED: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 131
CONTEMPORARY AMPEREX TECHNOLOGY CO., LIMITED: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 132
BYD COMPANY LTD.: COMPANY OVERVIEW


TABLE 133
BYD COMPANY LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 134
BYD COMPANY LTD.: DEALS, JANUARY 2021–AUGUST 2026


TABLE 135
SCHNEIDER ELECTRIC: COMPANY OVERVIEW


TABLE 136
SCHNEIDER ELECTRIC: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 137
SCHNEIDER ELECTRIC: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 138
SCHNEIDER ELECTRIC: DEALS, JANUARY 2021–AUGUST 2026


TABLE 139
SCHNEIDER ELECTRIC: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 140
VERTIV GROUP CORP.: COMPANY OVERVIEW


TABLE 141
VERTIV GROUP CORP.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 142
VERTIV GROUP CORP.: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 143
VERTIV GROUP CORP.: DEALS, JANUARY 2021–AUGUST 2026


TABLE 144
VERTIV GROUP CORP.: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 145
EATON: COMPANY OVERVIEW


TABLE 146
EATON: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 147
EATON: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 148
ABB: COMPANY OVERVIEW


TABLE 149
ABB: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 150
ABB: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 151
ABB: DEALS, JANUARY 2021–AUGUST 2026


TABLE 152
ABB: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 153
SIEMENS ENERGY: COMPANY OVERVIEW


TABLE 154
SIEMENS ENERGY: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 155
SIEMENS ENERGY: DEALS, JANUARY 2021–AUGUST 2026


TABLE 156
SIEMENS ENERGY: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 157
DELTA ELECTRONICS, INC.: COMPANY OVERVIEW


TABLE 158
DELTA ELECTRONICS, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 159
DELTA ELECTRONICS, INC.: DEALS, JANUARY 2021–AUGUST 2026


TABLE 160
DELTA ELECTRONICS, INC.: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 161
HITACHI ENERGY LTD: COMPANY OVERVIEW


TABLE 162
HITACHI ENERGY LTD: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 163
HITACHI ENERGY LTD: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 164
HITACHI ENERGY LTD: DEALS, JANUARY 2021–AUGUST 2026


TABLE 165
HITACHI ENERGY LTD: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 166
FLUENCE: COMPANY OVERVIEW


TABLE 167
FLUENCE: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 168
FLUENCE: DEALS, JANUARY 2021–AUGUST 2026


TABLE 169
SAFT: COMPANY OVERVIEW


TABLE 170
SAFT: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 171
SAFT: DEALS, JANUARY 2021–AUGUST 2026


TABLE 172
WÄRTSILÄ: COMPANY OVERVIEW


TABLE 173
WÄRTSILÄ: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 174
WÄRTSILÄ: DEALS, JANUARY 2021–AUGUST 2026


TABLE 175
ENERSYS: COMPANY OVERVIEW


TABLE 176
ENERSYS: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 177
ENERSYS: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 178
ENERSYS: EXPANSIONS, JANUARY 2021–AUGUST 2026


TABLE 179
HUAWEI DIGITAL POWER TECHNOLOGIES CO., LTD.: COMPANY OVERVIEW


TABLE 180
HUAWEI DIGITAL POWER TECHNOLOGIES CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 181
GS YUASA: COMPANY OVERVIEW


TABLE 182
GS YUASA: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 183
EXIDE TECHNOLOGIES: COMPANY OVERVIEW


TABLE 184
EXIDE TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 185
EXIDE TECHNOLOGIES: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 186
TOSHIBA INTERNATIONAL CORPORATION: COMPANY OVERVIEW


TABLE 187
TOSHIBA INTERNATIONAL CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 188
EAST PENN MANUFACTURING COMPANY: COMPANY OVERVIEW


TABLE 189
ZINCFIVE, INC.: COMPANY OVERVIEW


TABLE 190
ACTIVE POWER INC.: COMPANY OVERVIEW


TABLE 191
SKELETON TECHNOLOGIES: COMPANY OVERVIEW


TABLE 192
VYCON: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
DATA CENTER ENERGY STORAGE SYSTEM MARKET SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
MARKET SCENARIO


FIGURE 3
GLOBAL DATA CENTER ENERGY STORAGE SYSTEM MARKET, 2022–2032


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN DATA CENTER ENERGY STORAGE SYSTEM MARKET, 2021–2026


FIGURE 5
DISRUPTIONS INFLUENCING GROWTH OF DATA CENTER ENERGY STORAGE SYSTEM MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS IN DATA CENTER ENERGY STORAGE SYSTEM MARKET, 2026–2032


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST CAGR IN DATA CENTER ENERGY STORAGE SYSTEM MARKET DURING FORECAST PERIOD


FIGURE 8
GROWING RETROFIT DEMAND AS EXISTING DATA CENTERS ADAPT TO HIGHER POWER DENSITY AND RESILIENCE REQUIREMENTS TO CREATE LUCRATIVE OPPORTUNITIES FOR MARKET PLAYERS


FIGURE 9
NORTH AMERICA TO DOMINATE MARKET DURING FORECAST PERIOD


FIGURE 10
BESS SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 11
CLOUD & HYPERSCALE DATA CENTERS SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 12
EXTENDED BACKUP POWER (UPS COMPANION) SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 13
IT & TELECOMMUNICATIONS SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 14
CHINA TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 15
DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN DATA CENTER ENERGY STORAGE SYSTEM MARKET


FIGURE 16
NUMBER OF DATA CENTERS ACROSS KEY COUNTRIES


FIGURE 17
DATA CENTER ENERGY STORAGE SYSTEM MARKET: PORTER’S FIVE FORCES ANALYSIS


FIGURE 18
DATA CENTER ENERGY STORAGE SYSTEM MARKET: SUPPLY CHAIN ANALYSIS


FIGURE 19
DATA CENTER ENERGY STORAGE SYSTEM MARKET: ECOSYSTEM MAPPING


FIGURE 20
AVERAGE SELLING PRICE TREND OF UPS-GRADE BATTERY PACKS, BY REGION, 2022–2025


FIGURE 21
IMPORT DATA RELATED TO HS CODE 850760, BY KEY COUNTRY, 2021–2025 (USD THOUSAND)


FIGURE 22
EXPORT DATA RELATED TO HS CODE 850760, BY KEY COUNTRY, 2021–2025 (USD THOUSAND)


FIGURE 23
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS


FIGURE 24
DATA CENTER ENERGY STORAGE SYSTEM MARKET: INVESTMENT AND FUNDING SCENARIO, 2019–2026


FIGURE 25
LIST OF MAJOR PATENTS RELATED TO DATA CENTER ENERGY STORAGE SYSTEMS, 2015–2025


FIGURE 26
FUTURE APPLICATIONS OF DATA CENTER ENERGY STORAGE SYSTEMS


FIGURE 27
DATA CENTER ENERGY STORAGE SYSTEM MARKET: DECISION-MAKING FACTORS


FIGURE 28
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR KEY APPLICATIONS


FIGURE 29
KEY BUYING CRITERIA, BY APPLICATIONS


FIGURE 30
ADOPTION BARRIERS & INTERNAL CHALLENGES


FIGURE 31
IT & TELECOMMUNICATIONS SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 32
EXTENDED BACKUP POWER (UPS COMPANION) SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 33
BATTERY ENERGY STORAGE SYSTEMS SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 34
CLOUD & HYPERSCALE DATA CENTERS SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 35
NORTH AMERICA TO ACCOUNT FOR THE LARGEST MARKET SHARE DURING THE FORECAST PERIOD


FIGURE 36
NORTH AMERICA: DATA CENTER ENERGY STORAGE SYSTEM MARKET SNAPSHOT


FIGURE 37
ASIA PACIFIC: DATA CENTER ENERGY STORAGE SYSTEM MARKET SNAPSHOT


FIGURE 38
EUROPE: DATA CENTER ENERGY STORAGE SYSTEM MARKET SNAPSHOT


FIGURE 39
DATA CENTER ENERGY STORAGE SYSTEM MARKET: REVENUE ANALYSIS OF KEY COMPANIES, 2021–2025 (USD BILLION)


FIGURE 40
RANKING OF KEY PLAYERS IN DATA CENTER ENERGY STORAGE SYSTEM MARKET, 2025


FIGURE 41
DATA CENTER ENERGY STORAGE SYSTEM MARKET SHARE ANALYSIS, 2025


FIGURE 42
PRODUCT COMPARISON


FIGURE 43
DATA CENTER ENERGY STORAGE SYSTEM MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 44
DATA CENTER ENERGY STORAGE SYSTEM MARKET: COMPANY FOOTPRINT


FIGURE 45
DATA CENTER ENERGY STORAGE SYSTEM MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 46
EV/EBITDA


FIGURE 47
ENTERPRISE VALUE


FIGURE 48
YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND FIVE-YEAR STOCK BETA OF KEY MANUFACTURERS


FIGURE 49
TESLA: COMPANY SNAPSHOT


FIGURE 50
PANASONIC HOLDINGS CORPORATION: COMPANY SNAPSHOT


FIGURE 51
SAMSUNG SDI CO., LTD.: COMPANY SNAPSHOT


FIGURE 52
LG ENERGY SOLUTION: COMPANY SNAPSHOT


FIGURE 53
CONTEMPORARY AMPEREX TECHNOLOGY CO., LIMITED: COMPANY SNAPSHOT


FIGURE 54
BYD COMPANY LTD.: COMPANY SNAPSHOT


FIGURE 55
SCHNEIDER ELECTRIC: COMPANY SNAPSHOT


FIGURE 56
VERTIV GROUP CORP.: COMPANY SNAPSHOT


FIGURE 57
EATON: COMPANY SNAPSHOT


FIGURE 58
ABB: COMPANY SNAPSHOT


FIGURE 59
SIEMENS ENERGY: COMPANY SNAPSHOT


FIGURE 60
DELTA ELECTRONICS, INC.: COMPANY SNAPSHOT


FIGURE 61
FLUENCE: COMPANY SNAPSHOT


FIGURE 62
WÄRTSILÄ: COMPANY SNAPSHOT


FIGURE 63
ENERSYS: COMPANY SNAPSHOT


FIGURE 64
GS YUASA: COMPANY SNAPSHOT


FIGURE 65
RESEARCH DESIGN


FIGURE 66
KEY DATA FROM SECONDARY SOURCES


FIGURE 67
KEY DATA FROM PRIMARY SOURCES


FIGURE 68
KEY INDUSTRY INSIGHTS


FIGURE 69
BREAKDOWN OF INTERVIEWS WITH EXPERTS


FIGURE 70
MATRIX CONSIDERED FOR DEMAND-SIDE ANALYSIS


FIGURE 71
BOTTOM-UP APPROACH


FIGURE 72
TOP-DOWN APPROACH


FIGURE 73
METHODOLOGY FOR SUPPLY-SIDE SIZING OF DATA CENTER ENERGY STORAGE SYSTEM MARKET (1/2)


FIGURE 74
METHODOLOGY FOR SUPPLY-SIDE SIZING OF DATA CENTER ENERGY STORAGE SYSTEM MARKET (2/2)


FIGURE 75
DATA TRIANGULATION


FIGURE 76
RESEARCH ASSUMPTIONS


FIGURE 77
RESEARCH LIMITATIONS


FIGURE 78
RISK ASSESSMENT


Methodology

This research encompassed four primary actions to assess the current market size of data center energy storage systems. Comprehensive secondary research was conducted to gather information on the market, the peer market, and the parent market. The subsequent stage involved corroborating these findings, assumptions, and dimensions with industry specialists across the oil value chain through primary research. The total market size is ascertained with both top-down and bottom-up methodologies. Subsequently, market segmentation analysis and data triangulation were employed to ascertain the dimensions of the market segments and subsegments.  

Secondary Research

The research approach employed to assess and project the data center energy storage systems market initiates with the collection of revenue data from prominent suppliers using secondary research. During the secondary research, many sources, including D&B Hoover's, Bloomberg BusinessWeek, Factiva, the World Bank, and industry magazines, were used to identify and compile information for this study. The secondary sources comprised annual reports, press releases, and investor presentations from corporations; white papers; accredited periodicals; writings by esteemed authors; announcements from regulatory agencies; trade directories; and databases. Vendor offerings have been considered to ascertain market segmentation.

Primary Research

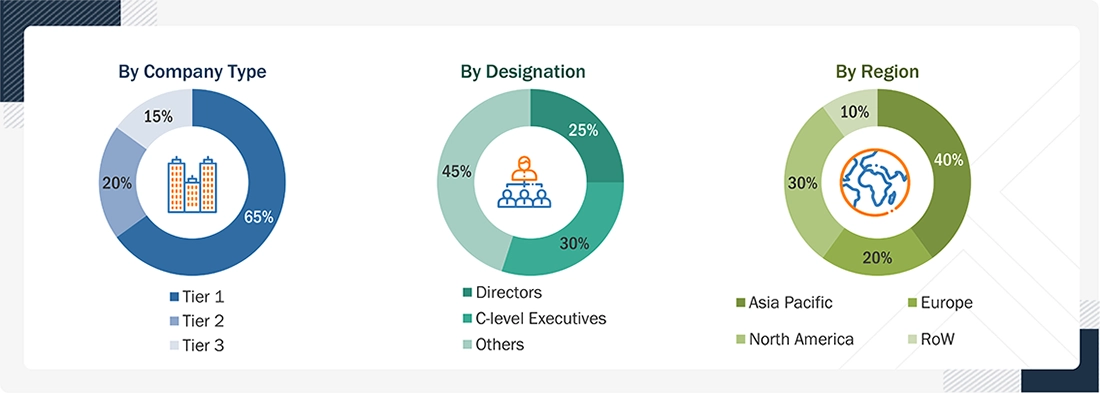
The data center energy storage systems market comprises several stakeholders, such as manufacturers, suppliers, traders, associations, and regulatory organizations, in the supply chain. The demand side of the data center energy storage systems market is primarily driven by data center operators, developers, and enterprises seeking reliable power, greater energy flexibility, and improved management of increasing electricity requirements. Growing investments in hyperscale, colocation, and enterprise data centers, along with the expansion of AI, cloud computing, and digital services, are strengthening demand. On the supply side, the market comprises energy storage manufacturers, power equipment providers, and system integrators offering solutions across different storage technologies and applications. Suppliers are increasingly expanding their offerings to address backup power, peak demand management, renewable energy integration, and the evolving electricity requirements of modern data centers. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information. The following is the breakdown of the primary respondents:

Data Center Energy Storage Systems Market Size, and Share

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

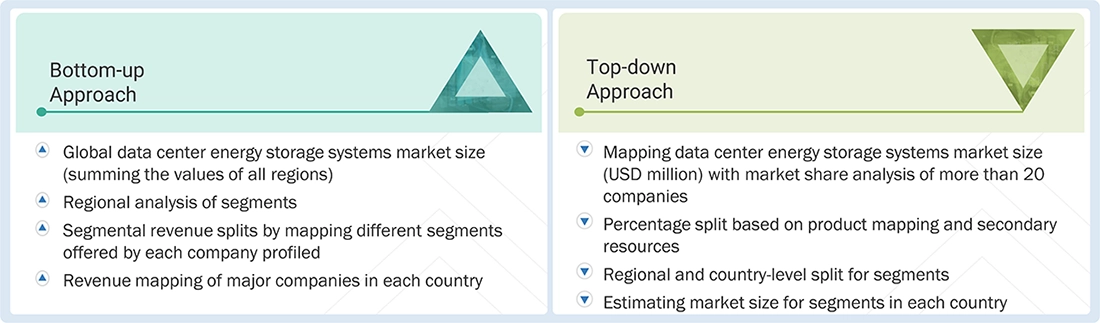
Both the top-down and bottom-up approaches were used to estimate and validate the total size of the data center energy storage systems market. These methods were also widely used to determine the sizes of various market subsegments. The research methodology used to estimate the market size included the following:

  • The key players were identified through extensive primary and secondary research.
  • The value chain and market size of the data center energy storage systems market, in terms of value, were determined through primary and secondary research.
  • All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
  • All possible parameters that affect the market covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
  • The research included the study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from key leaders, such as CEOs, directors, and marketing executives.

Data Center Energy Storage Systems Market: Top-Down and Bottom-Up Approach

Data Center Energy Storage Systems Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size using the market size estimation processes as explained above, the market was split into several segments and sub-segments. To complete the overall market engineering process and obtain the exact statistics for each market segment and subsegment, data triangulation and market breakdown procedures were employed, as applicable. The market size was calculated globally by summing country- and regional-level data.

Market Definition

Data center energy storage systems are energy storage solutions deployed within or alongside data center facilities to store electricity and make it available when required, supporting reliable power availability and efficient management of the facility’s electricity needs. They can be used to provide additional power during interruptions, manage periods of high electricity demand, support the use of renewable energy, and improve overall power resilience. Data center energy storage systems include solutions such as battery energy storage systems (BESS), flywheel energy storage systems (FESS), supercapacitors and other energy storage technologies (hydrogen energy storage), depending on the requirements and operating conditions of the facility. These systems can be deployed across enterprise, hyperscale, and colocation data centers and can support applications ranging from backup power and power quality conditioning to peak shaving, renewable energy integration, and grid-related services.

Key Stakeholders

  • Data Center Energy Storage Systems Manufacturers
  • Data Center Energy Storage Systems Suppliers
  • Data Center Energy Storage Systems Traders, Distributors, and Suppliers
  • Investment Banks and Private Equity Firms
  • Raw Material Suppliers
  • Government and Research Organizations
  • Consulting Companies/Consultants in Chemicals and Materials Sectors
  • Industry Associations
  • Contract Manufacturing Organizations (CMOs)
  • NGOs, Governments, Investment Banks, Venture Capitalists, and Private Equity Firms

Report Objectives

  • To define, describe, and forecast the size of the global data center energy storage systems market in terms of value
  • To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and industry-specific challenges, influencing the growth of the global data center energy storage systems market
  • To analyze and forecast the size of various segments (energy storage technology, data center type, application, and enterprise vertical/end user) of the data center energy storage systems market based on four major regions—North America, Asia Pacific, Europe, and Rest of the World, along with key countries in each of these regions
  • To strategically profile the key players in the market and comprehensively analyze their core competencies

Available customizations:

With the given market data, MarketsandMarkets offers customizations according to client-specific needs.
The following customization options are available for the report:

  • Additional country-level analysis of the data center energy storage systems market
  • Profiling of additional market players (up to 5)

Product Analysis

  • Product matrix, which gives a detailed comparison of the product portfolio of each company.

Company Information

  • Detailed analysis and profiles of additional market players (up to five)

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Data Center Energy Storage Systems Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Data Center Energy Storage Systems Market

DMCA.com Protection Status
popup img